Morgan Stanley has revised its outlook for Apple Inc. (AAPL), adjusting the price target to $355 from a previous $360, while maintaining an Overweight rating.
This alteration stems from the newly introduced iPhone lineup’s pricing strategy, which is exerting downward pressure on average selling prices and gross margins.
This revision is particularly noteworthy given that Apple’s stock has surged over 30% in the past six months, while profit projections have remained relatively stagnant, indicating limited potential for further price appreciation—albeit Morgan Stanley continues to express optimism regarding Apple’s long-term product strategy.
The financial institution’s analysts emphasize that Apple’s product pipeline stands as one of the most enticing seen in over a decade, although the recent iPhone launch has not significantly transformed its earnings trajectory.
With shares currently valued at $333 and the company’s market capitalization at $4.86 trillion, the assessment indicates that Apple’s valuation exceeds what InvestingPro deems a fair value benchmark.
At present, Apple trades at 38.5 times earnings, with consensus projections for fiscal 2026 estimating earnings at $8.93 per share.
Under the leadership of newly appointed Chief Executive Officer John Ternus, who took over on September 1, Apple is said to be entering an era that Morgan Stanley characterizes as one of the most exhilarating and pivotal periods of innovation in recent memory.
The firm anticipates that iPhone unit sales are poised to experience growth for an unprecedented fourth consecutive year, marking the first time since fiscal 2015, which could potentially lead to a compound annual growth rate of approximately 13% in earnings per share from fiscal 2026 through fiscal 2028.
Morgan Stanley projects that Apple will achieve earnings of around $10 per share in fiscal 2027 and nearly $11 in fiscal 2028, figures that align closely with market consensus estimates.
The forecast for the September quarter remains favorable, bolstered by robust iPhone production volumes, increased Mac revenue, advantageous adjustments in service pricing, and tariff refunds.
Conversely, the outlook for the December quarter appears more ambiguous. Analysts caution that current market estimates may not accurately reflect the staggered iPhone launch, leading to overly optimistic shipment forecasts for that particular period.
Pricing Pressure Meets Product Momentum
The recent fall launch cycle unveiled the iPhone 18 Pro and iPhone 18 Pro Max, which began shipping on September 18 following an earlier announcement.
These latest models are powered by the A20 Pro chip and are equipped with Apple’s advanced Siri AI capabilities.
In conjunction with the iPhone rollout, Apple refreshed its Mac lineup, introducing a Mac mini with M6 and M5 Pro chips, as well as a Mac Studio driven by the M5 Max and M5 Ultra processors, both available from September 22.
Morgan Stanley noted that its forecasting model exhibited only marginal changes after assessing post-launch pricing, specifications, delivery timelines, Siri AI enhancements, revised service pricing, and supply chain insights.
The lower-than-anticipated pricing of iPhones is somewhat counterbalanced by heightened shipment predictions, sustained outperformance in the Mac segment, and modest improvements within the services domain.
Additionally, the firm identified rising memory costs as a counteracting influence. While the new product cycle is projected to contribute to increased revenue, escalating component expenses and declining average selling prices for iPhones are anticipated to largely offset these gains, resulting in a largely unchanged earnings outlook.
Diverging Views on Wall Street
Needham maintained a Hold rating, emphasizing competitive threats stemming from Meta and other AI-centric enterprises that could jeopardize Apple’s ecosystem.
Bank of America, advocating for a Buy rating, highlighted concerns that agentic AI may undermine Apple’s authority over discovery and transaction initiation, even with persistent iPhone sales. The bank perceived Apple as a prospective beneficiary of AI advancements at the edge.
Morgan Stanley itself characterized agentic AI as both a nascent risk and a promising opportunity for the corporation.
As Siri AI is enhanced with personal context understanding, on-screen awareness, and cross-application functionalities, Apple positions itself strategically within the race for agentic interfaces.
Leadership Transition and Legal Headwinds
This analytical reassessment is occurring concurrently with Apple’s leadership transition under Ternus, who has expressed intentions to expedite workflows, streamline staff numbers, and increase revenue through services.
Sources indicate that the new CEO aspires to deviate from Apple’s conventional spring and fall launch schedule, advocating instead for continuous product releases throughout the year—a shift that insiders estimate could require several years for full implementation.
Reportedly, several engineering program managers, including numerous directors, have been granted several weeks to secure new positions within the company or face potential layoffs by year-end.
The programs affected include the development of the Vision Pro headset, Siri, and other AI-related software projects.
Legally, the UK Competition Appeal Tribunal has granted permission for a consumer class action against Apple and Amazon to proceed.
This case pertains to a 2018 agreement concerning the sale of Apple products on Amazon’s UK platform, scrutinizing Apple’s commercial practices under regulatory oversight.
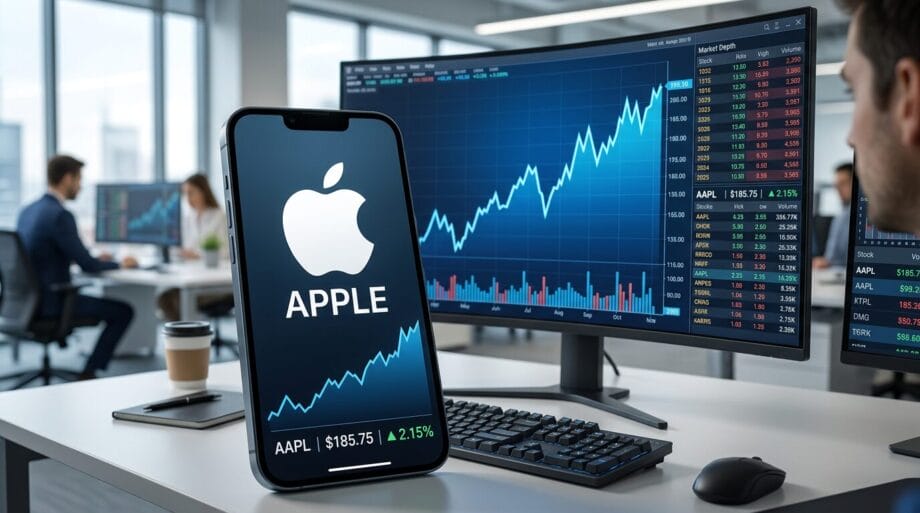
In 2026, Apple shares have appreciated by nearly 23%, trailing behind the State Street Technology Select Sector SPDR ETF, which has witnessed gains exceeding 35% during the same timeframe.
This disparity underscores the challenges facing the company: a formidable product cycle and thriving services growth must now substantiate a valuation that allows for minimal margin for error.
Source link: Finance.biggo.com.